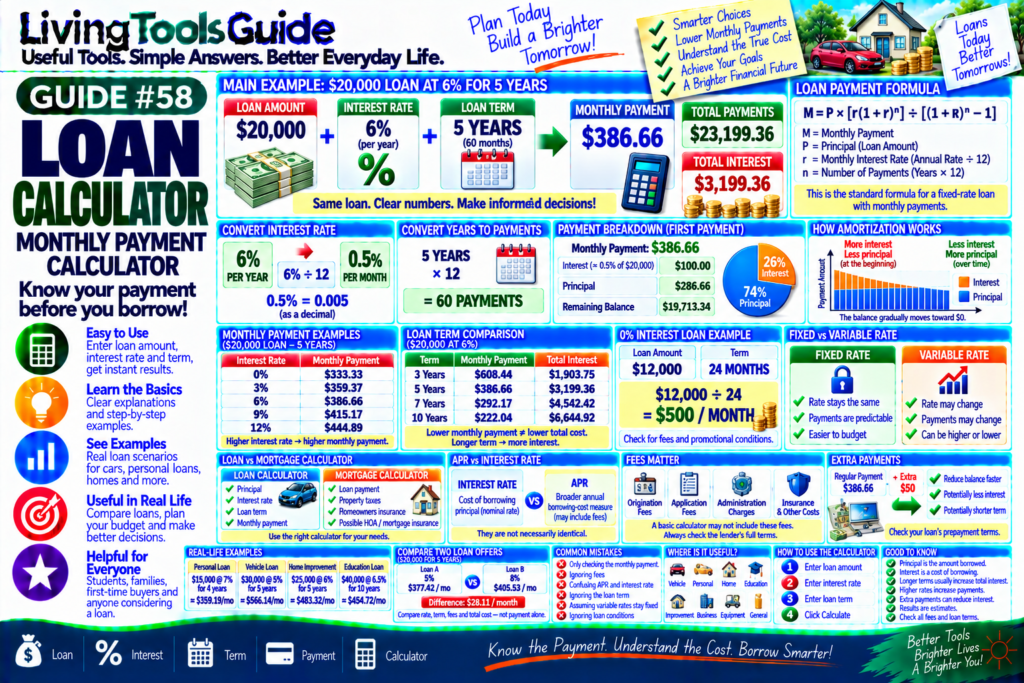
When you borrow money, knowing the loan amount alone isn’t enough. You also need to understand how much you may pay each month, how much interest may accumulate, and the total amount repaid over the life of the loan.
A Loan Calculator can estimate these figures using the:
💰 Loan Amount
📊 Interest Rate
📅 Loan Term
For example, suppose you borrow:
$20,000
at:
6% Annual Interest
for:
5 Years
With standard monthly payments and monthly compounding, the estimated payment is approximately:
$386.66 PER MONTH
Over 60 payments:
Total Payments ≈ $23,199.36
Total Interest ≈ $3,199.36
Important: Loan calculator results are estimates. Actual payments and borrowing costs can differ because of fees, compounding conventions, payment timing, taxes, insurance, variable rates, rounding, lender rules, and other loan terms.
What Is a Loan Calculator?
A Loan Calculator estimates the payment required to repay a loan over a specified period.
For a typical fixed-rate amortizing loan, you enter:
💵 Principal
The amount borrowed.
📈 Annual Interest Rate
The percentage charged for borrowing.
📅 Loan Term
How long you have to repay the loan.
The calculator can then estimate:
MONTHLY PAYMENT
as well as:
TOTAL INTEREST
and:
TOTAL REPAYMENT
What Is Loan Principal?
The principal is the amount you initially borrow.
For example, if you borrow:
$25,000
your initial principal is:
$25,000
As payments are made, part of each payment generally reduces principal and part pays interest.
What Is Interest?
Interest is the cost charged for borrowing money.
Suppose you have a:
6% annual interest rate
That percentage is used according to the loan’s terms to determine interest charges.
For a standard calculator using monthly periodic interest, the monthly rate is:
Annual Rate ÷ 12
So:
6% ÷ 12
=
0.5% PER MONTH
or as a decimal:
0.005
Monthly Loan Payment Formula
For a standard fixed-rate amortizing loan, a commonly used formula is:
M = P × [r(1+r)ⁿ] ÷ [(1+r)ⁿ − 1]
Where:
M = Monthly Payment
P = Principal
r = Monthly Interest Rate
n = Number of Monthly Payments
Step 1 — Convert Annual Rate to Monthly Rate
Suppose:
Annual Rate = 6%
Convert to decimal:
6 ÷ 100 = 0.06
Then divide by 12:
0.06 ÷ 12
=
0.005
Monthly rate:
0.5%
Step 2 — Convert Years to Months
Suppose the loan term is:
5 Years
Calculate:
5 × 12
=
60 MONTHS
Therefore:
n = 60
Complete Loan Example
Suppose:
Loan Amount = $20,000
Interest Rate = 6%
Loan Term = 5 years
Monthly rate:
0.005
Number of payments:
60
Using the amortization formula gives an estimated monthly payment of:
$386.66
Total Repayment
Once you know the monthly payment, an approximate total of scheduled payments is:
Total Payments = Monthly Payment × Number of Payments
Using the unrounded calculated payment internally:
≈ $23,199.36
This represents the approximate total of principal and interest under the assumed loan terms.
Total Interest
Formula:
Total Interest = Total Payments − Principal
Example:
$23,199.36 − $20,000
=
≈ $3,199.36
So the approximate borrowing cost from interest alone is:
$3,199.36
This does not include additional lender fees or other charges.
Quick Example — $10,000 Loan
Suppose:
Principal = $10,000
Rate = 5%
Term = 3 Years
Number of payments:
3 × 12 = 36
Monthly interest rate:
0.05 ÷ 12
≈
0.0041667
Estimated monthly payment:
≈ $299.71
Approximate total payments:
≈ $10,789.52
Approximate total interest:
≈ $789.52
What Happens When the Interest Rate Increases?
Higher interest rates generally mean higher payments and greater total interest when the principal and term remain unchanged.
For example, consider:
$20,000 for 5 Years
Approximate monthly payments:
| Annual Rate | Monthly Payment |
|---|---|
| 0% | $333.33 |
| 3% | $359.37 |
| 6% | $386.66 |
| 9% | $415.17 |
| 12% | $444.89 |
This illustrates why comparing rates can matter.
What Happens When the Loan Term Increases?
A longer term usually:
⬇️ Lowers the Monthly Payment
but can:
⬆️ Increase Total Interest
because the balance remains outstanding longer.
For example, suppose:
$20,000 at 6%
Approximate results:
| Term | Monthly Payment | Approx. Total Interest |
|---|---|---|
| 3 Years | $608.44 | $1,903.75 |
| 5 Years | $386.66 | $3,199.36 |
| 7 Years | $292.17 | $4,542.42 |
| 10 Years | $222.04 | $6,644.92 |
This demonstrates an important trade-off:
Lower Monthly Payment ≠ Lower Total Cost
What Is Loan Amortization?
An amortizing loan is gradually repaid through scheduled payments.
Each payment generally contains:
INTEREST + PRINCIPAL
Early in many amortizing loans, a larger portion of the payment goes toward interest.
As the balance decreases, the interest portion generally becomes smaller and more of the payment goes toward principal.
Simple Amortization Example
Suppose the monthly payment is:
$386.66
At the beginning of a $20,000 loan with a 0.5% monthly interest rate:
First month’s approximate interest:
$20,000 × 0.005
=
$100
Approximate principal paid:
$386.66 − $100
=
$286.66
New approximate balance:
$20,000 − $286.66
=
$19,713.34
The following month’s interest is calculated on the lower balance under this simplified amortization model.
0% Interest Loan
If the loan genuinely has:
0% Interest
the calculation is much simpler.
Formula:
Payment = Principal ÷ Number of Payments
Example:
$12,000
for:
24 Months
Calculation:
12,000 ÷ 24
=
$500 PER MONTH
However, always check whether fees or promotional conditions apply.
Loan Term in Years vs Months
Your calculator may allow users to enter either.
5 Years
=
60 Months
10 Years
=
120 Months
15 Years
=
180 Months
Formula:
Months = Years × 12
APR vs Interest Rate
An advertised interest rate and an APR (Annual Percentage Rate) are not necessarily the same.
The interest rate generally describes the rate charged on the borrowed principal.
APR is designed to represent borrowing cost on an annual basis and may incorporate certain fees or charges depending on applicable rules and the loan.
Therefore, don’t assume that entering an APR into a calculator designed for a nominal interest rate will reproduce a lender’s exact payment.
When comparing loans, it is also important to understand the difference between an interest rate and APR, because APR can include additional loan fees.
Loan Fees Matter
Some loans may include:
💵 Origination Fees
📄 Application Fees
🏦 Administrative Charges
🛡️ Insurance
or other costs.
For example, borrowing:
$10,000
with a:
$300 Fee
may result in an economic cost that isn’t fully represented by a calculator using only principal and interest.
Always review the lender’s actual disclosures.
Fixed vs Variable Interest Rates
🔒 Fixed Rate
The interest rate remains fixed according to the loan agreement.
For a fully amortizing fixed-rate loan, the scheduled principal-and-interest payment is generally predictable.
🔄 Variable Rate
The rate can change according to the loan terms.
This means future payments or loan costs may also change.
A basic Loan Calculator usually assumes:
A FIXED INTEREST RATE
unless specifically designed for variable-rate loans.
Extra Payments
Paying more than the required payment may reduce principal faster on loans that permit it.
This can potentially:
⬇️ Reduce Total Interest
and:
⏱️ Shorten the Repayment Period
However, loan terms differ.
Check whether:
Prepayment is allowed
Extra payments are applied to principal
and whether:
Prepayment penalties or other restrictions apply
Loan Calculator vs Mortgage Calculator
Both calculators can use similar amortization mathematics.
However, a Mortgage Calculator may include additional housing-related costs such as:
🏠 Property Taxes
🛡️ Homeowners Insurance
🏘️ HOA Fees
and sometimes:
💵 Mortgage Insurance
Your Mortgage Calculator — GUIDE #33 is therefore more appropriate for detailed home-loan planning.
Loan Calculator vs Savings Calculator
These calculators use interest in opposite ways.
💳 Loan Calculator
Interest is generally:
A COST TO THE BORROWER
💰 Savings Calculator
Interest or investment growth can:
INCREASE YOUR BALANCE
This makes your Savings Calculator — GUIDE #42 a useful related guide.
Example — Personal Loan
Suppose you borrow:
$15,000
at:
7%
for:
4 Years
Estimated monthly payment:
≈ $359.19
Approximate total of payments:
≈ $17,241.23
Approximate total interest:
≈ $2,241.23
Actual lender figures may differ.
Example — Vehicle Loan
Suppose:
Loan Amount = $30,000
Rate = 5%
Term = 5 Years
Estimated monthly payment:
≈ $566.14
Approximate total payments:
≈ $33,968.22
Approximate interest:
≈ $3,968.22
A vehicle purchase can also involve taxes, registration, down payments, trade-ins, fees, or other costs that a basic loan calculator may not include.
Comparing Two Loan Offers
Suppose both loans are:
$20,000 for 5 Years
Loan A
5% interest
Monthly payment:
≈ $377.42
Loan B
8% interest
Monthly payment:
≈ $405.53
Difference:
≈ $28.11 PER MONTH
Over 60 payments, that difference can become significant.
Compare more than just the monthly payment—consider the rate, fees, term, and total borrowing cost.
Common Loan Calculation Mistakes
❌ Looking Only at Monthly Payment
A lower monthly payment can come from a longer loan term and may increase total interest.
❌ Ignoring Fees
Interest isn’t always the only borrowing cost.
❌ Confusing APR and Interest Rate
They may represent different measures.
❌ Forgetting Loan Term
The number of payments significantly affects cost.
❌ Assuming Variable Rates Stay Constant
Future rates may change.
❌ Ignoring Loan Conditions
Prepayment, late-payment, and other rules can matter.
Where Is a Loan Calculator Useful?
A Loan Calculator can help estimate payments for:
🚗 Vehicle Loans
💳 Personal Loans
🏠 Home-Related Loans
🎓 Education Loans
🏗️ Improvement Loans
💼 Business Loans
🛠️ Equipment Financing
💰 General Borrowing
The specific terms and fees of these products can vary considerably.
How to Use the Loan Calculator
Using your LivingToolsGuide calculator is simple:
1 — Enter Loan Amount
Example:
$20,000
2 — Enter Annual Interest Rate
6%
3 — Enter Loan Term
5 Years
4 — Click Calculate
Estimated result:
Monthly Payment
$386.66
Total Payments
≈ $23,199.36
Total Interest
≈ $3,199.36
Calculate Your Loan Payment Now
Considering a loan and want to estimate the monthly payment?
Use our Loan Calculator to estimate monthly principal-and-interest payments, total interest, and total repayment based on your loan amount, interest rate, and term.
💰 Loan | 📈 Interest | 📅 Term | 💵 Payment | 🧮 Calculator
Know the Payment. Understand the Cost. Borrow Smarter!